The platform paid, for a while. The dashboard showed the balance growing at 1.5% a day, or 20% a month, from "AI arbitrage", "liquidity mining", "cross-exchange spreads" or a trading bot with a name. Withdrawals worked at first — that is what made you add more, and what made you bring in the two friends who now also want answers. Then a withdrawal stalled behind a "verification fee", or the site went dark, or the Telegram group was deleted overnight. This article is for the person who has just realised what it was, and wants a straight answer to the only question that matters: is any of it coming back?
What you were actually in
Call it what the regulators call it: a Ponzi scheme. The "returns" were not generated by anything. They were paid out of the deposits of the people who joined after you, which is why the scheme needed the referral tiers, the recruitment bonuses and the constant urging to reinvest. The trading dashboard was a web page with numbers on it; there was no exchange account behind it, and there were no trades. The "arbitrage" framing is the current favourite because it sounds mechanical and low-risk — a bot exploiting price differences between exchanges — and because most people cannot check whether such a bot exists. It did not.
Two variants are worth telling apart, because they end differently.
The platform scheme. A website or app with a login, a balance and a withdrawal button; deposits by crypto to an address the platform gives you. This is structurally the same object as the fake exchanges we describe on the fake exchange page — the difference is the story: "trade for yourself" there, "we trade for you" here.
The network scheme. No platform to speak of; money moves person to person, through a "leader" who collects deposits and pays out "profits" by hand, with a downline of recruiters. These are older, slower, often run inside a community — a church, a diaspora, a workplace — and the person who took your money is frequently someone who also lost theirs.
Why this is harder than a theft — and why it is still a case
A wallet drain is a theft: funds left without your consent, and the investigation starts from a single transaction. In a Ponzi scheme you sent the money yourself, repeatedly, to an address the scheme gave you. That does not make it legal — it is fraud — but it changes the investigation in three ways.
Your money was pooled. Your deposits landed in collection addresses together with hundreds of others'. Some of that pool went out again as "withdrawals" to earlier participants, some went to the operators, some sat as float. There is no longer a specific sum that is "yours" on-chain; there is a share of a pool, and a share of whatever remains of it.
The operators cashed out continuously, not once. A thief moves a lump and hides it. A scheme operator extracts steadily over months, through exchanges, OTC desks and payment channels, in amounts sized to avoid attention. By the time the scheme collapses, most of the extraction has already happened.
There are many victims and one set of facts. Which is a disadvantage — the operators' assets, if found, will be divided — and an advantage, because the evidence of a hundred victims filed together is what moves a police unit or a court that would not move for one.
What decides whether anything comes back
The same three questions we apply to every case, on the scam types page, with the answers weighted for this type.
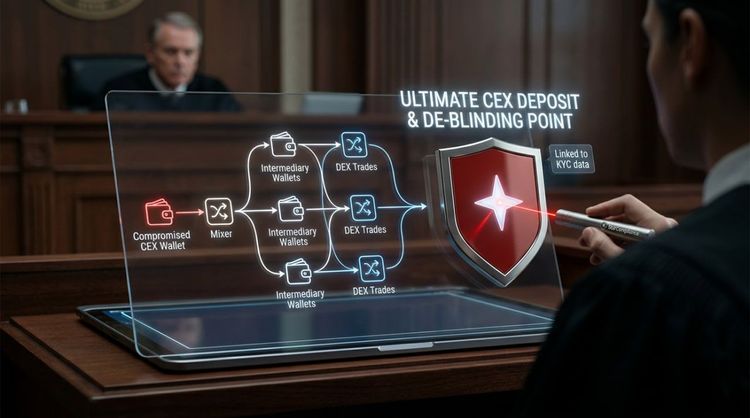
- Did the operators' funds reach a centralised exchange, and are they still there? This is the whole case. Scheme operators usually convert to fiat at some point, and often at a venue with a compliance desk. If a consolidation address can be traced to an account at such a venue, and a freeze request supported by a police report reaches that desk while the balance is there, there is something to recover. If the extraction is complete and the funds are through OTC channels or in jurisdictions that do not respond, there is not.
- How early is it? Weeks after collapse, the consolidation addresses may still hold float and the last withdrawals may still be sitting on an exchange. Months after, they do not. A scheme that has just stopped paying is a live case; one that stopped a year ago is usually an evidence file for a criminal prosecution, which is a different thing from a recovery.
- Is there a defendant? Some schemes have named promoters, registered companies, real addresses — even if the trading was fictional. Those can be sued, prosecuted, and in large cases put into receivership, where a court-appointed administrator gathers what remains and distributes it to victims over years. Others are a Telegram handle and a domain registered through a proxy, and the only route is the on-chain one.
We do not publish a percentage for this category; it would be invented. What we do publish is our overall figure — 68% success rate on accepted cases · measured over the past 24 months — and the word accepted is doing the work: we decline cases where we see no realistic prospect, and Ponzi cases where the extraction is complete and the endpoints are unreachable are among the ones we decline at the first call, at no cost to the person asking.
What to do now, in this order
- Stop paying. Completely. The "withdrawal fee", the "tax", the "account upgrade to unlock funds" — these are the scheme's last extraction from people who have already been extracted from. No legitimate platform charges a fee to release your own balance.
- Save the platform before it disappears. Screenshots of the dashboard, the balance, the transaction history, the terms, the team page. The domain, the app, the group chats and who administered them. The wallet addresses you deposited to and the transaction hashes of every deposit — from your own wallet or exchange history, not from the platform's page.
- Coordinate with the other victims. This is the step that is specific to schemes: a police report filed in coordination by many victims carries more weight than a single complaint. Groups form quickly after a collapse; the useful ones collect deposit addresses and amounts in one place, not grievances.
- Report it. To the national cybercrime portal and to the police where you live, with the deposit hashes — our guide to where and how to report a crypto scam covers the order and what to include. A police report is not a formality: it is what a provisional freeze at an exchange needs in order to become a formal one.
- Get the collection addresses flagged. The scheme's deposit and consolidation addresses, submitted to the screening providers that exchanges rely on, so that the next time those funds touch a compliance desk they stop. In our process this happens within four hours of intake.
- Get the money trail established, if the loss justifies it. A trace from the collection addresses through consolidation to the exchange endpoints is what turns "we were defrauded" into "the proceeds are in this account at this venue" — the only sentence a freeze request can be built on. That is investigative work; it is what we do, and the assessment of whether it is worth doing is free and answered within two business hours.
The scheme after the scheme
Within days of a collapse, victims are contacted. A "recovery agency" has been "assigned your case". A "regulator" needs a fee to release compensation. A "law firm" has already recovered funds for other members of the group and needs a retainer. Sometimes the contact comes from the same people who ran the scheme, using the victim list they already hold. Every one of these is a second fraud aimed at people known to be desperate, and the FBI's Internet Crime Complaint Center has issued public advisories about exactly this pattern. Nobody is assigned to you. No agency will assign your case to a firm that contacts you. We do not cold-message victims. Before you engage anyone — including us — run the checklist on the verification page.
What we do not do
Recover a balance that existed only on the scheme's dashboard: the "profits" were never real and nothing can return them; what is at stake is your deposits. Take a case where the source of the funds cannot be confirmed — that applies to a victim as much as to anyone. Take Monero cases. Practise law: where a case goes to a court, that work is carried out by partner lawyers in the relevant jurisdiction. And promise an outcome. Recovery in this category is decided by whether the operators' money can be found at a venue that answers, and by what a court does with it; nobody can guarantee either, and the ones who do are running the scheme after the scheme.
If the funds are traceable and the loss is significant, send us the transaction hashes: the assessment is free and answered within two business hours, including when the answer is that there is nothing to pursue. Write through the contact page or message @StarCompliance on Telegram.
Questions people ask after a Ponzi collapse
The platform still shows my balance. Does that mean the money is still there?
No. The dashboard is a database entry; it never corresponded to assets. The only balances that exist are the ones on-chain, at the addresses the scheme collected into and wherever they moved from there.
I recruited others. Am I liable?
That is a legal question for a lawyer in your jurisdiction, and the answer depends on what you knew and what you received. In investigative terms, a participant who was paid referral commissions may also be a victim, and their deposit records are evidence like anyone else's.
I lost $15,000. Is it worth pursuing?
On your own, an investigation is rarely economic at that size; our published threshold is a loss from $200,000, with smaller cases reviewed individually.
The operators are in another country. Is that the end?
Not by itself. The operators' location matters less than where their funds are — the exchange that holds the proceeds may be in a third jurisdiction that responds to freeze requests. Cases with several jurisdictions take longer, six to thirty-six months in our experience, and the legal steps in each are taken by lawyers admitted there.
Someone offers to recover my Ponzi losses for a fee. Should I pay?
No. A fee to release compensation or "recovered" funds is the scheme after the scheme. Nobody is assigned to your case, and we do not cold-message victims. Before engaging anyone — including us — run the checklist on our verification page.
What should I save before the platform disappears?
Screenshots of the dashboard, the balance, the transaction history, the terms and the team page; the domain, the app and the group chats; and the deposit addresses and transaction hashes of every deposit — from your own wallet or exchange history, not from the platform's page.
This article is informational material, not legal advice, and no outcome is promised: decisions on freezing and releasing funds are made by exchanges, issuers and courts. Figures are from StarCompliance casework and are published, with the period each covers, on our figures page.